
How Do You Add a Payment Link to an NFC Business Card?
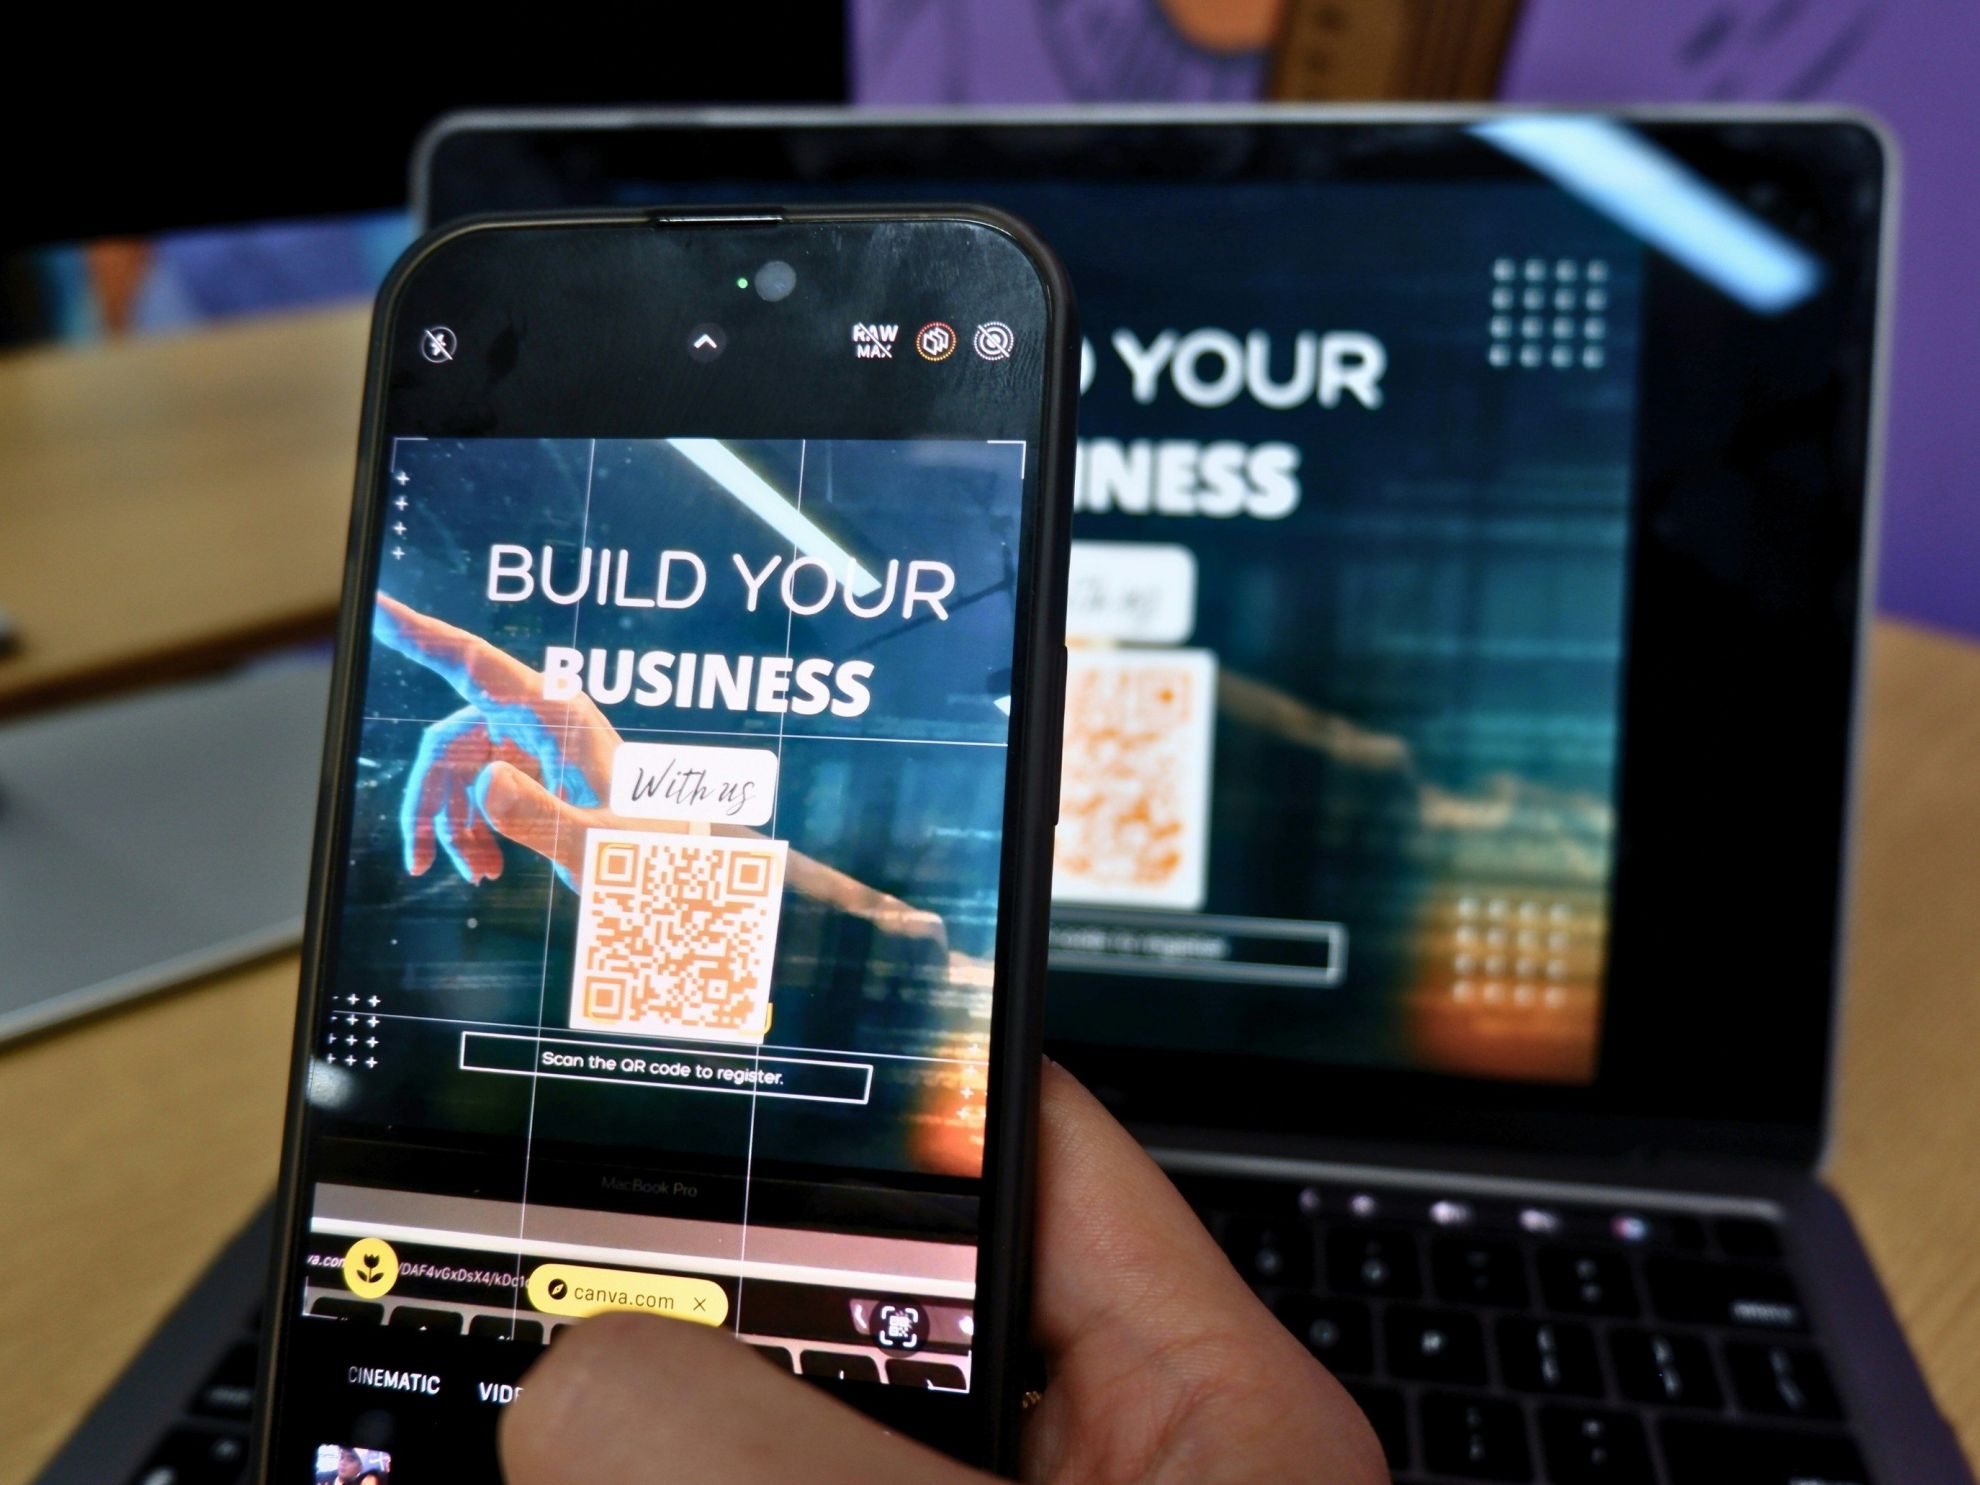
How do you add a payment link to an NFC business card so that a single tap on someone’s phone opens a checkout page instead of just saving your contact details? This is one of the most practical questions facing founders, freelancers, and sales teams who want their networking to convert into revenue. If you are wondering how do you add a payment link to an NFC business card, the short answer is that the NFC chip stores a URL, and that URL points to a hosted payment page, a payment-processor checkout, or a link-management profile that contains your payment buttons. In the first 100 to 150 words of this guide we have already repeated the central question twice, and we will keep returning to how do you add a payment link to an NFC business card as we walk through the underlying technology, the four main methods, step-by-step setup, security, real case studies, and the mistakes that quietly kill conversion rates. A well-configured payment-enabled NFC card turns a handshake into a frictionless “tap to pay” moment that traditional paper cards could never deliver.
Why You Should Add a Payment Link to an NFC Business Card
The decision to add a payment link to an NFC business card is usually driven by a simple economics problem: every extra step between a customer’s intent and a completed payment reduces conversion. Paper cards get lost. Verbal “just Venmo me” instructions get forgotten. Typing a long URL is error-prone. When you embed a payment link into an NFC business card, the prospect’s phone does the work the instant they tap.
From a buyer psychology standpoint, the tap creates a tiny moment of delight. The phone vibrates, a browser or wallet opens, and the payment surface is already there. That immediacy is why creators, consultants, tradespeople, and pop-up retailers increasingly choose to add a payment link to an NFC business card rather than handing over a static card with a printed QR that merely points to a homepage.
Another reason is measurability. A hosted payment link can be unique per card, per campaign, or per salesperson. You can see exactly how many taps converted into payments. That data loop is impossible with paper. When you add a payment link to an NFC business card with a trackable URL, you turn a networking object into a measurable sales channel.
Understanding What an NFC Business Card Actually Stores
Before we go deeper into how do you add a payment link to an NFC business card, it helps to understand what the chip holds. An NFC business card is not a miniature computer. It is a passive tag, typically an NTAG213, NTAG215, or NTAG216 chip with a small antenna. It stores a small amount of memory (144, 504, or 888 bytes respectively) and, most importantly, it can store a single URL or a small set of text records.
When a phone taps the card, the phone reads that URL and opens it. The card itself does not process payments. All the payment logic lives on the destination page. So when you add a payment link to an NFC business card, you are really choosing what URL the chip points to and what that page does once it loads.
This distinction matters because it shapes your entire approach. You are not “putting a payment processor on the card.” You are putting a doorway on the card, and the doorway leads to a room that handles money. The security, branding, and conversion of that room are yours to design.
The Four Main Approaches to Adding a Payment Link
There are four realistic ways to add a payment link to an NFC business card. Each has trade-offs in cost, control, branding, and settlement speed.
Approach 1: Direct Payment Processor Checkout Link
In this approach, you generate a shareable payment link from a processor such as Stripe, Square, PayPal, or Wise, then write that link directly onto the NFC chip. The tap opens the processor’s hosted checkout.
Pros:
- Fastest setup; no website required.
- Funds settle directly to your processor account.
- High trust because the customer sees a familiar brand.
Cons:
- Limited branding; the page looks like the processor, not you.
- Hard to add multiple payment methods or upsells.
- Some processors generate links that expire or require login.
Approach 2: Link-in-Bio or Link Management Profile
Here you create a profile on a link tool (Linktree, Beacons, Tapkit, or a self-hosted page) and place your payment buttons there. The NFC chip stores the profile URL.
Pros:
- Strong branding and layout control.
- You can show multiple payment options, a tip jar, and your social links.
- Easy to update the destination without rewriting the chip.
Cons:
- An extra hop before the payment page, which can lower conversion slightly.
- Some platforms charge a subscription.
- Load speed depends on the platform.
Approach 3: Your Own Hosted Payment Page
You build a dedicated page on your own website (for example, yoursite.com/pay) that embeds a checkout widget or redirects to a processor. The NFC chip stores that URL.
Pros:
- Full control over design, copy, and analytics.
- No third-party branding between you and the customer.
- You own the customer relationship and the data.
Cons:
- Requires web hosting and some technical setup.
- You are responsible for security and PCI considerations (use embedded widgets, do not handle raw card data).
- More upfront time.
Approach 4: NFC Card Platform With Built-In Payments
Some NFC business card vendors bundle a dashboard where you configure a payment link in their app, and the chip points to their short link that resolves to your payment page.
Pros:
- Zero technical work; configure in a mobile app.
- Often includes tap analytics and profile management.
Cons:
- Recurring platform fees.
- You depend on the vendor’s short-link domain staying alive.
- Less control if the vendor changes pricing or shuts down.
For most small businesses, Approach 2 or 3 is the sweet spot when they ask how do you add a payment link to an NFC business card, because branding and control matter more than raw setup speed.
Comparison Table: Payment Link Methods for NFC Cards
The table below compares the four approaches so you can choose the right setup when you add a payment link to an NFC business card.
| Feature | Direct Processor Link | Link Management Profile | Own Hosted Page | NFC Platform Built-In |
|---|---|---|---|---|
| Setup time | Minutes | 1 to 2 hours | Half a day | Minutes |
| Branding control | Low | Medium to high | Highest | Low to medium |
| Recurring cost | None (processor fees only) | Free to paid tiers | Hosting only | Monthly subscription |
| Multiple payment methods | Limited | Yes | Yes | Vendor dependent |
| Analytics | Basic | Good | Best (if configured) | Good |
| Dependency risk | Low | Medium (platform) | Low | High (vendor) |
| Best for | Quick testing | Solopreneurs | Established brands | Non-technical users |
For almost every professional deployment, we recommend either a link management profile or a lightweight own hosted page when you add a payment link to an NFC business card, because the customer should feel they are paying you, not a faceless processor.
Step-by-Step: How to Add a Payment Link to an NFC Business Card
Here is the practical sequence most people follow, regardless of which approach they choose.
Step 1: Choose Your Payment Destination
Decide what the tap should open. Options include a Stripe Payment Link, a Square checkout, a PayPal.me page, a tip page, or a product-specific buy page. Write down the exact URL. When you add a payment link to an NFC business card, this URL is the single most important asset you control.
Step 2: Shorten or Brand the URL
Long processor URLs are ugly and can exceed the comfortable memory of some NTAG chips if packed with tracking parameters. Use a custom short domain (pay.yourname.com) or a reputable shortener. Keep the final URL under about 100 characters to ensure reliable writes on NTAG213 chips.
Step 3: Acquire an NFC Write Tool
You need a way to write the URL to the chip. Options include an NFC-enabled phone with a free app (NXP TagWriter, NFC Tools), a desktop NFC encoder if you are producing many cards, or the vendor’s configuration app if you bought a platform card. For a single card, the phone app is enough.
Step 4: Write the URL to the Card
Open the app, select “Write URL,” paste your payment link, hold the phone to the card, and confirm. The app reports success. Test by tapping with a second phone. This is the literal moment you add a payment link to an NFC business card.
Step 5: Test the Full Flow
Do not stop at “the page opened.” Complete a real test payment of one cent or use a test mode. Confirm the amount, the receipt, and the settlement. A broken payment page behind a working tap is worse than no card at all.
Step 6: Add a Fallback QR
Print a small QR code on the card back that encodes the same payment link. Phones without NFC, or users who are unsure how to tap, can scan. This redundancy protects conversion when you add a payment link to an NFC business card for public-facing use.
Step 7: Track and Iterate
Use UTM parameters or a unique path per card to measure taps versus payments. If taps are high but payments are low, the destination page is the problem. If taps are low, the card instruction (“Tap to pay”) is unclear.
Why the Destination Page Design Matters More Than the Chip
The chip is dumb. It only points. The page it points to does all the selling. When you add a payment link to an NFC business card, invest most of your energy in the page. A good payment page has a single clear action, shows the amount or product, displays trust signals (lock icon, processor logo, refund policy), and loads in under two seconds on mobile.
An infographic we often share with clients maps the tap journey: tap, phone wakes, browser opens, page loads, customer reads amount, customer pays. Each step has a drop-off risk. The page step is where most revenue leaks. Treat the page like a landing page, not a backend form.
Security and Compliance Considerations
When you add a payment link to an NFC business card, you must respect payment security. The golden rule: never collect raw card numbers on your own server. Use embedded checkout widgets from a PCI-compliant processor so the card data goes straight to them. This keeps you out of PCI scope and protects your customers.
Also consider that an NFC tag is readable by anyone in range. The URL itself is not secret, and that is fine, because the payment page should be safe to open publicly. Do not encode sensitive data (prices hidden behind login, customer lists) directly on the chip. The chip should only ever hold a public URL.
For regional compliance, note that some jurisdictions require clear disclosure that a tap will open a payment request. A small line on the card such as “Tap to open secure payment page” satisfies this and improves trust.
Case Study 1: Freelance Photographer Converts Consult Calls
A wedding photographer was tired of sending six follow-up messages to collect deposits. She asked how do you add a payment link to an NFC business card so clients could pay the booking deposit on the spot. She used Approach 3: a hosted page on her site with a Stripe Payment Link for a fixed deposit amount. The NFC chip stored her pay subdomain URL. At bridal expos, she handed the card and said “tap to lock your date.” Within two months, on-the-spot deposit rate rose from roughly 20 percent to 65 percent. The card paid for itself in the first event.
Case Study 2: Coffee Cart Adds Tips at Markets
A mobile coffee cart operator wanted contactless tips without a full POS. He chose Approach 2, a link profile with a Square tip page and his social links. The NFC chip on his counter card stored the profile URL. Customers tapped, chose a tip amount, and paid. Over a festival weekend he collected 40 percent more tip revenue than the previous cash-only setup, and the QR fallback captured the few Android phones that hesitated to tap.
Case Study 3: B2B Sales Rep Tracks Channel Performance
A software sales rep gave every rep on his team a uniquely coded NFC card pointing to a demo-signup payment page. By adding a payment link to an NFC business card with a per-rep UTM path, the manager measured which reps’ networking actually converted. One rep’s card drove three times the paid trials of another. The data reshaped the team’s event strategy within a quarter.
Choosing the Right NFC Chip Memory
When you add a payment link to an NFC business card, memory size is rarely the bottleneck because a URL is short. NTAG213 (144 bytes) handles almost any clean URL. If you also want to store a vCard contact record alongside the payment link, you need NTAG215 or NTAG216, or you store the vCard on the destination page and let the chip hold only the URL. Many modern digital business card platforms solve this by storing everything on the profile page and keeping the chip lean.
Multiple Payment Methods on One Card
A common worry is “can one card take cards, Apple Pay, and bank transfer?” The answer is yes, at the page level. The chip stores one URL. That URL opens a page that offers buttons for Stripe (cards and wallets), PayPal, and bank transfer via a processor that supports it. So when you add a payment link to an NFC business card, you are not limited to one rail; you are limited only by what your destination page supports.
Common Mistakes That Kill Conversion
- Encoding a homepage instead of a payment page, forcing the customer to hunt for the pay button.
- Using a URL so long it fails to write on a low-memory chip.
- Forgetting to test a real payment, discovering the page is broken at the event.
- No QR fallback for non-NFC phones.
- A payment page that is not mobile-optimized, with tiny buttons and slow load.
- Hiding fees or lacking a refund note, which erodes trust at the exact moment of payment.
- Relying on a vendor short link that expires if you stop subscribing.
- Printing the card without a clear “Tap to pay” instruction.
Each of these is avoidable. When you ask how do you add a payment link to an NFC business card, treat the setup like a mini checkout funnel and remove every avoidable step.
Updating the Link Without Rewriting the Chip
A clever trick: encode a stable redirect URL that you control, then change the destination on your server. This way, if you switch processors or run a promotion, you do not need to rewrite every physical card. When you add a payment link to an NFC business card with a redirect layer, the chip stays constant and the destination stays flexible. This is especially valuable for large batches sourced from a factory, where rewriting thousands of cards is impractical.
Sourcing NFC Business Cards at Scale
If you plan to issue cards to a team or include them in product packaging, buying单个 hand-written cards is inefficient. A sourcing partner can help you order NTAG215 cards pre-encoded with your redirect URL, printed with your branding, and QC-tested for tap reliability. For example, if you are planning a custom NFC program, you can review capabilities and request a quote through the manufacturer directory at https://www.duomy.com, which connects you with vetted card plants that handle combined NFC and printing production. Having a partner also helps you standardize specs so every reorder is consistent.
We also recommend reviewing the broader custom card catalog and production guidelines on https://www.duomy.com before finalizing your chip choice and print finish, since substrate and antenna layout interact with both tap range and print durability.
Comparison Table: NFC Chip Choices for Payment Cards
| Chip model | Usable memory | Best use when adding payment link | Approx. read range | Notes |
|---|---|---|---|---|
| NTAG213 | 144 bytes | URL-only payment link | Up to 50 mm | Cheapest, sufficient for most |
| NTAG215 | 504 bytes | URL plus vCard or extra records | Up to 60 mm | Good balance |
| NTAG216 | 888 bytes | Rich profile data on chip | Up to 70 mm | Overkill if page holds data |
| MIFARE Classic | 1 KB | Closed systems only | Up to 100 mm | Not ideal for open web links |
For nearly all payment-link use cases, NTAG213 or NTAG215 is the right call when you add a payment link to an NFC business card.
Measuring Success: Metrics That Matter
When you add a payment link to an NFC business card, track these numbers:
- Tap count (via redirect or UTM).
- Page open to payment-start rate.
- Payment completion rate.
- Average payment value.
- Refund or dispute rate.
A healthy tap-to-payment rate for a clear single-action page is often 30 to 60 percent. If yours is below 20 percent, audit the page, not the card.
Advanced Tip: Dynamic Amounts Via Query Parameters
Some processors let you pre-fill the amount using query parameters in the URL, such as pay.example.com/checkout?amount=50. When you add a payment link to an NFC business card for a fixed product, bake the amount in so the customer only confirms. For variable invoices, leave the amount editable on the page. This small choice removes a decision and lifts completion.
When a Payment Link Is the Wrong Choice
Not every NFC card should open a payment page. If your networking is purely relationship-building and a payment ask feels premature, a contact-only card is better. If you operate in a regulated industry where taking instant payments requires licensing, consult compliance first. And if your typical transaction is large and negotiated, a “request a quote” page beats a payment page.
Frequently Asked Questions
Can you add a payment link to an NFC business card that already has a contact profile?
Yes. The simplest method is to store a profile URL on the chip and put both the contact save and the payment button on that page. If the chip currently holds only a vCard, rewrite it (NTAG chips are rewritable) to hold the profile URL instead, then design the page to offer “Save contact” and “Pay” side by side.
Does the NFC chip store my customer’s card details?
No. The chip only stores a public URL that opens a payment page. All card data is entered on the processor’s secure page and never touches the chip or your server if you use an embedded widget. This is why adding a payment link to an NFC business card is safe: the tag itself holds no financial information.
Which payment processors work best with an NFC tap card?
Stripe Payment Links, Square checkout, PayPal, and Wise all generate shareable links that work well. Stripe and Square offer clean mobile pages and strong branding control. Choose based on your region, fees, and whether you need wallets like Apple Pay or Google Pay, which Stripe and Square both support.
What if the customer’s phone does not support NFC?
Add a QR code on the card back encoding the same payment link. All modern smartphones scan QR codes without extra apps. This fallback is essential for public use and protects conversion when some attendees cannot tap.
How do I change the payment link later without rewriting the card?
Encode a redirect URL that you control, then point that redirect at your current payment page. When you switch processors or run a sale, update the redirect destination only. The physical cards keep working because the chip URL never changes.
Is it legal to put a payment request on a business card?
In most regions yes, as long as the page is a standard payment request and you disclose what the tap does. Avoid surprise charges and follow consumer protection rules about clear pricing and refunds. If you are unsure, have a payments-savvy advisor review your page.
How much does it cost to add a payment link to an NFC business card?
The card itself costs a few dollars for a single unit or under a dollar each at volume. The payment link is usually free to create; you pay standard processor fees (often 2.9 percent plus a fixed fee) only when a payment succeeds. Platform subscriptions, if used, are the main recurring cost.
Can one NFC card handle multiple currencies or payment methods?
Yes, at the page level. The chip stores one URL that opens a page offering multiple methods (cards, PayPal, bank transfer) and, with some processors, multiple currencies. The customer picks their preferred rail. The chip is not the limit; your destination page is.
Closing Thoughts
Learning how do you add a payment link to an NFC business card comes down to three principles: point the chip at a clean, mobile-first payment page; test a real transaction before you hand the card out; and add a QR fallback so nobody is left out. Do those three things and you convert a networking object into a quiet, always-open cash register. The technology is simple, the upside in collected deposits and tips is real, and the failure modes are easy to control with a redirect layer and a well-designed destination. Start with one card, measure the taps, and scale only after the funnel proves itself.
Tags: NFC business card, payment link, add payment link, NFC payment, tap to pay, Stripe payment link, NFC chip, contactless payment, digital business card, NFC card sourcing
Related Articles
Wholesale Industrial Sensors & Micro-Automation Components: Factory Direct Sourcing
Wholesale Industrial Sensors & Micro-Automation Components: Factory Direct Sourcing When sourcing industrial sensors and micro-automation components…
Read More
High-Stability Industrial Sensors & Analog Semiconductor Solutions
High-Stability Industrial Sensors & Analog Semiconductor Solutions High-Stability Industrial Sensors & Analog Semiconductor Solutions deliver the…
Read More
How to Navigate China Component Supplier Negotiations for First-Time Buyers?
How to Navigate China Component Supplier Negotiations for First-Time Buyers? Knowing how to navigate China component…
Read More